Oct 17, 6:01 AM
The Rent Inflation Paradox
Stagnant property values and relentless rent hikes create a bizarre threshold where owning beats leasing.
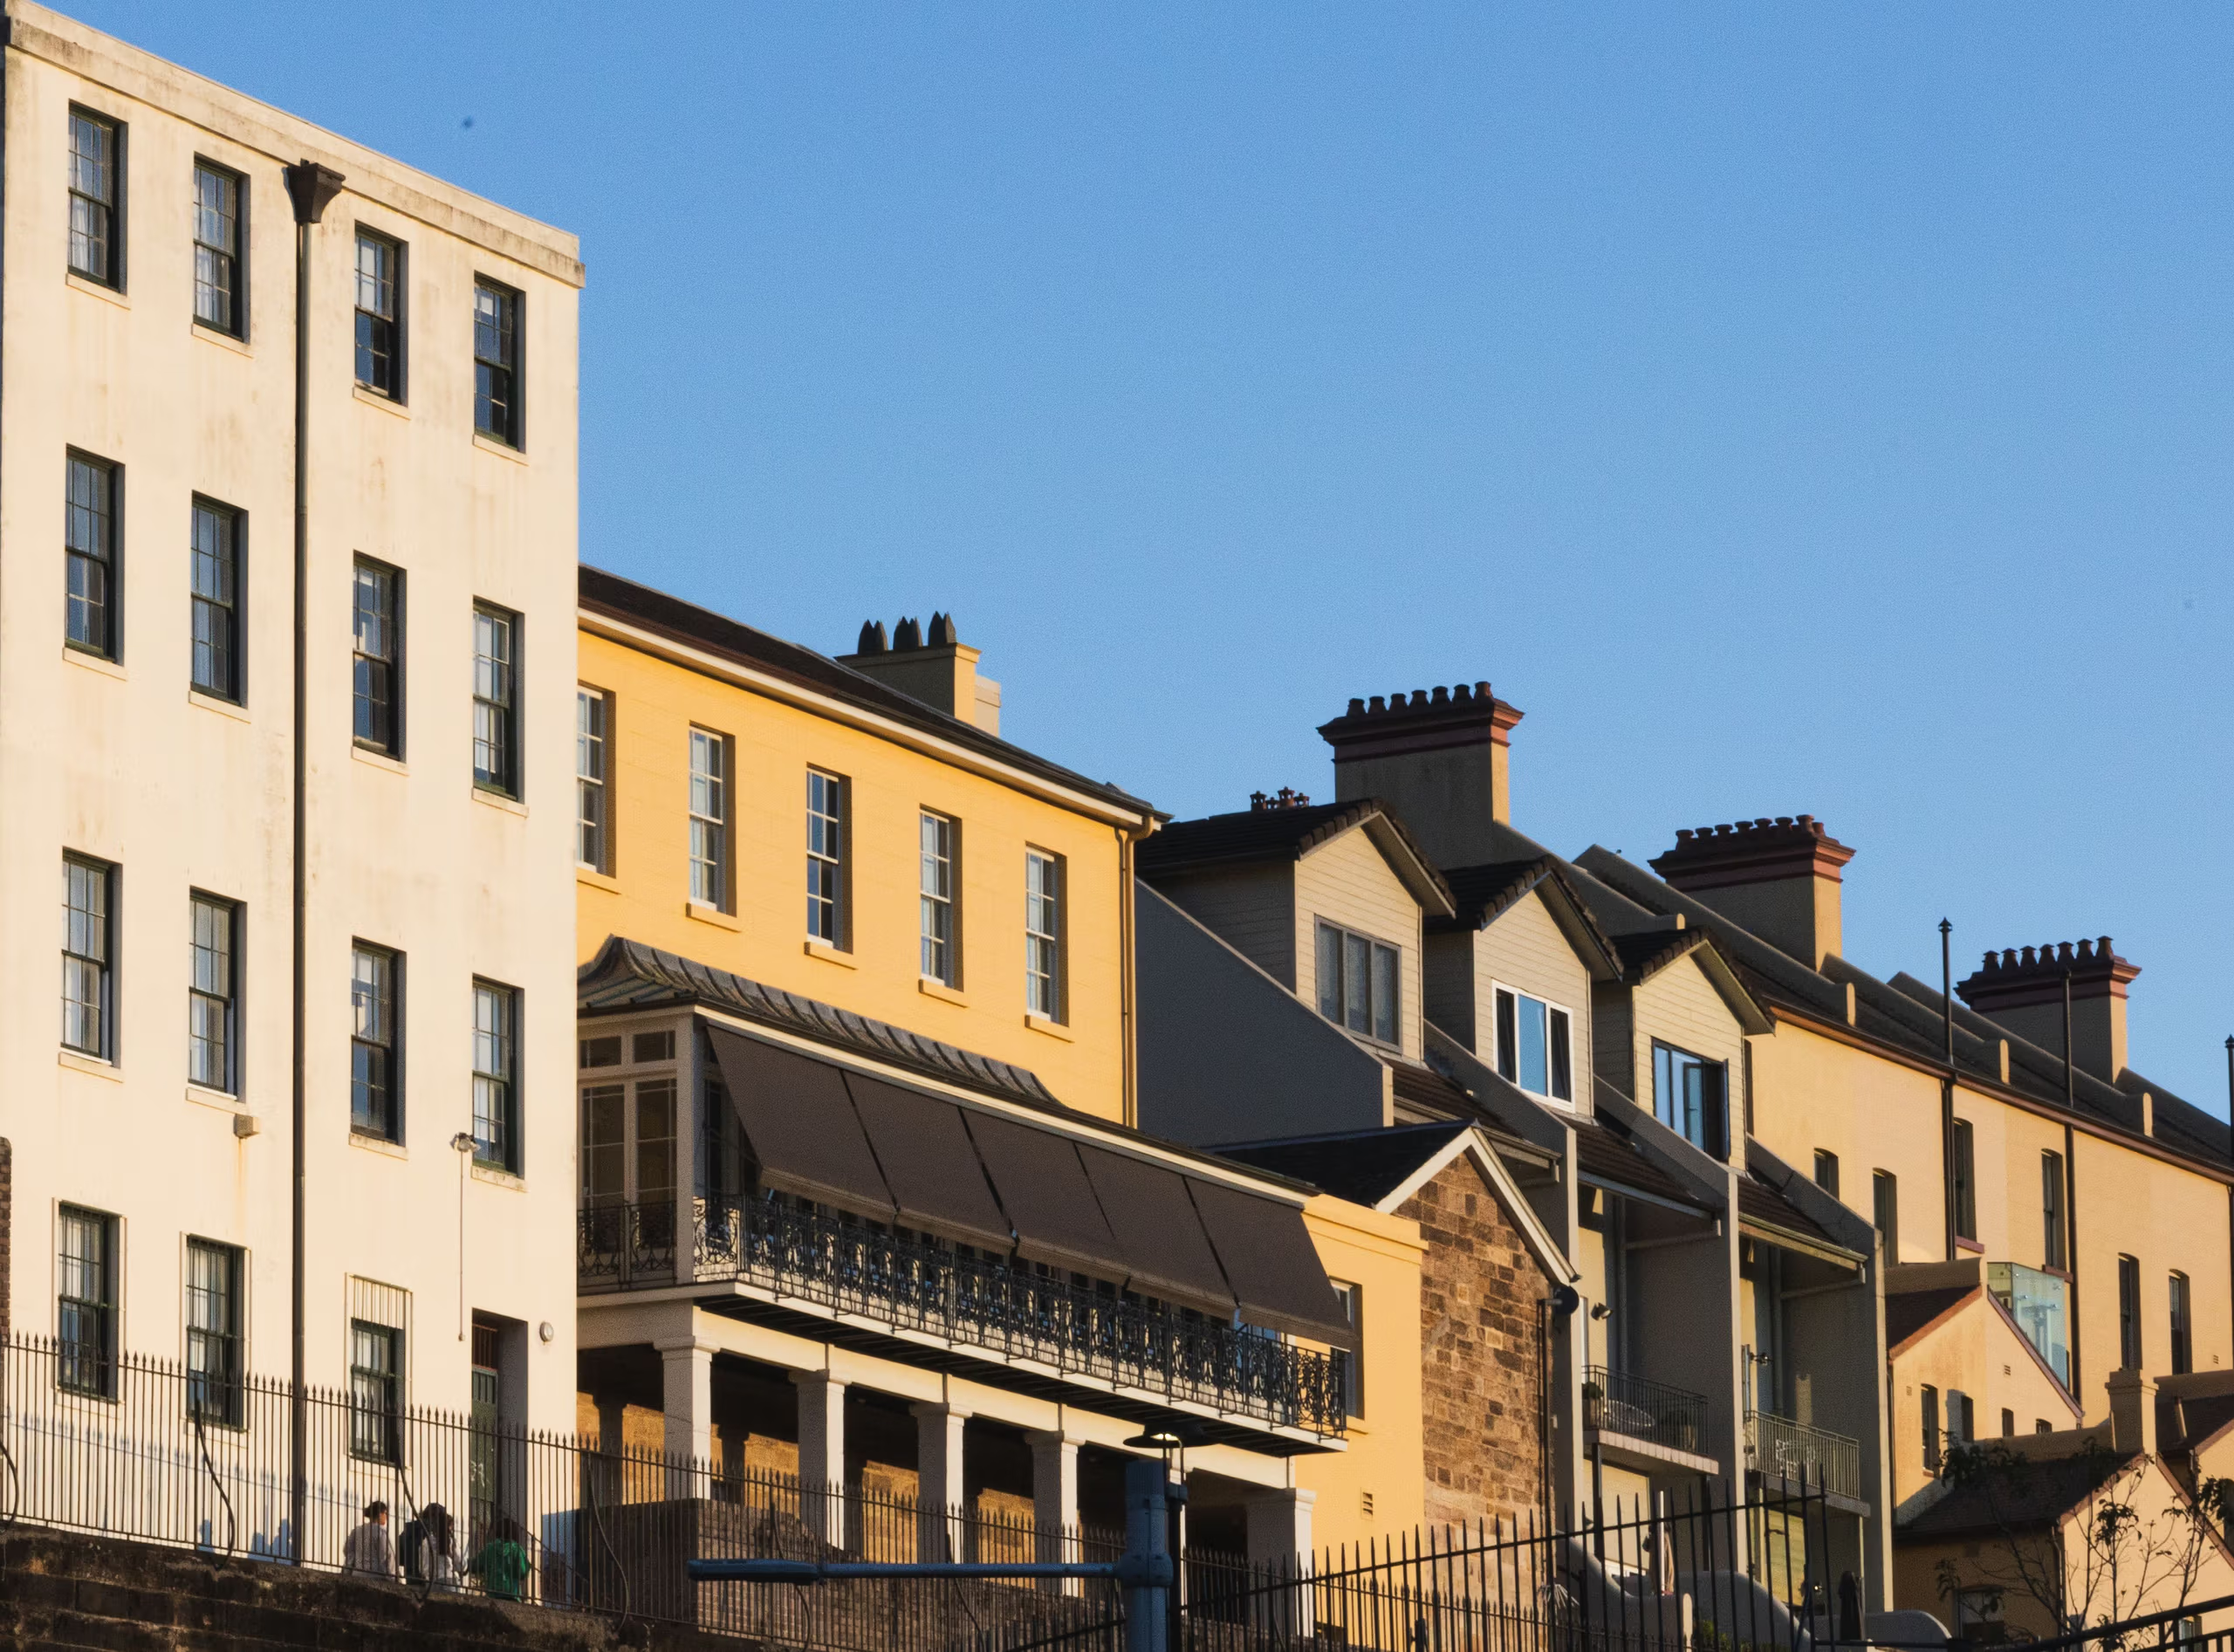
For years, the standard real estate rule dictated that renting offered flexibility at the price of equity, while buying demanded a substantial financial premium. A strange distortion in Australia's housing market is turning that calculation on its head. In pockets of the country, hand over your weekly earnings to a landlord, and you might actually be subsidising a lifestyle less affordable than simply buying the place yourself.
National rental figures hit a median of $713 per week after a 5.5 per cent surge over the year to September. At the same time, property values flatlined following six months of persistent drops. For a tenant calculating a standard 30-year mortgage at a 6.2 per cent interest rate with a 5 per cent deposit, the financial gap between servicing a landlord's asset and acquiring one's own has shrunk dramatically. Across one-tenth of Australian suburbs, home loan repayments now sit within $200 a week of local rents.
In select high-density enclaves, buying has crossed the threshold to become cheaper outright. Inner-city Melbourne precincts like Carlton, Southbank, and the central business district join parts of Darwin—where rents surged 11.6 per cent—in displaying this numerical inversion. Data from Cotality reveals that an influx of new apartment supply has suppressed purchase values in these urban pockets, even as tight rental availability drives lease prices higher. In Sydney suburbs such as Ultimo and Granville, or Canberra districts like Belconnen, the weekly difference between renting and buying a flat has dwindled to double digits.
This narrow margin is not merely an arithmetic curiosity; it reflects shifting pressures on property owners. Rising interest rates over the past year initially increased borrowing costs, but steep drops in property values—exceeding 10 per cent in certain areas—offset those hikes. Meanwhile, squeezed by regulations and holding costs, a steady stream of landlords is choosing to exit the market altogether, often offering their properties directly to sitting tenants looking to bypass the traditional market shuffle.
Whether this imbalance represents a permanent structural shift or a temporary market glitch depends entirely on property types. High-density apartment corridors and resource-rich regional towns dominated by temporary workers account for most of these outliers, whereas detached houses remain substantially more expensive to purchase than to lease. Should central bank interest rates hold steady while property values continue their downward glide, the financial argument for tenant-turned-buyer may harden further.
Written by Thorben Thiede thorben.thiede@alpineweekly.com